Knowing what to do if an insurance claim is denied matters more in Texas than in most states, because Texas gives policyholders statutory deadlines and remedies that many people never hear about.
A denial letter is a position, not a verdict. Carriers deny claims for reasons ranging from a real policy exclusion to a rushed adjustment or a misread inspection report. What matters next is why the denial happened, what the law requires of your insurer, and when it makes sense to speak with a San Angelo denied insurance claims lawyer.
Key Takeaways About Denied Insurance Claims in Texas
- A written denial must state the reasons for the rejection, which gives you something specific to answer.
- Texas insurers work under statutory deadlines to acknowledge, investigate, decide and pay claims.
- An insurer that misses those deadlines may owe 18 percent annual interest plus attorney's fees.
- Most Texas Insurance Code claims carry a two-year deadline, typically running from the denial.
- Appealing alone is possible, though denial letters are often written to discourage exactly that. A lawyer's role is to test the denial against the policy and the statute.
What Should I Do If My Insurance Company Denies My Claim in San Angelo, Texas?
Get the denial in writing, read it against your actual policy language, gather the documents and photos that prove the loss, and talk to a lawyer before you appeal. Texas sets firm deadlines for insurers and lets policyholders challenge bad-faith denials. Each policy is different, so a short conversation can clarify which path fits.
What Deadlines Does Texas Law Put on Your Insurance Company?
Texas law gives your insurer a clock, and it starts the day you report the loss. The Prompt Payment of Claims Act in Chapter 542 of the Texas Insurance Code sets the schedule below.
| What the insurer must do | Deadline |
| Acknowledge the claim, begin investigating, and request what it needs | 15 days after receiving notice of the claim |
| Notify you in writing that the claim is accepted or rejected | 15 business days after receiving everything it requested |
| Explain the delay if it cannot decide in time | Within that same window, with up to 45 more days to decide |
| Pay an accepted claim | 5 business days after the notice of acceptance |
Missing these deadlines has a price. An insurer out of compliance may be liable for the claim amount plus 18 percent annual interest as damages, together with reasonable attorney's fees.
Why Do Insurance Companies Deny Claims?
Most denials fall into a handful of categories, and only some hold up: a policy exclusion, alleged late notice, incomplete documentation, an alleged misstatement on the application, or a lapsed premium.
Wind and hail losses in West Texas draw their own version. The carrier concedes damage exists, then attributes it to age, poor maintenance or a prior storm rather than the one you reported.
When Is a Denial Considered Bad Faith in Texas?
A denial crosses into bad faith when the insurer handles the claim unfairly rather than simply reaching a conclusion you disagree with. Chapter 541 of the Texas Insurance Code lists unfair settlement practices that give policyholders a right to sue.
Those include refusing to pay without a reasonable investigation, failing to attempt a fair settlement once liability is reasonably clear, misrepresenting a policy provision, and failing to explain the basis for the denial. These claims generally must be filed within two years.
What Can You Recover If the Denial Was Wrongful?
In many cases, considerably more than the original claim amount: the benefits owed under the policy, the statutory interest penalty, attorney's fees, and in some circumstances additional damages where the insurer knowingly committed an unfair practice.
The same framework covers delayed insurance claims, where the carrier never formally denies anything and simply lets the file sit.
Steps That Often Help After a Denial
Policyholders typically find it useful to request a complete copy of the policy including all endorsements, then ask for the adjuster's file and any engineering or inspection report. Those documents are often more revealing than the denial letter itself.
Photograph the damage before repairs, keep receipts for temporary fixes, and log the date and substance of every call with the carrier. Filing a complaint with the Texas Department of Insurance also creates an independent record of the dispute.
When Should You Talk to a Lawyer About a Denied Claim?
Sooner is typically better when the loss is significant, when the denial reason does not match your policy language, when the carrier has gone quiet, or when an offer arrives with a release attached. Our role is to read the policy against the denial and pursue what the policy actually promised.
Denied Insurance Claim Questions, Answered
Can my insurance company cancel my policy because I filed a claim?
Texas limits mid-term cancellation, and the rules differ by policy type. Non-renewal at the end of a term is treated differently, and carriers must give advance written notice either way.
Does hiring a public adjuster affect my ability to sue later?
Not directly, though it can complicate things. A public adjuster negotiates claim value and cannot give legal advice or file suit. Anything you sign with one is worth reviewing first.
What if I already cashed the check the insurer sent?
Depositing a partial payment does not always waive the rest. A check marked full and final settlement, or paired with a signed release, may. Hold it and ask before you deposit.
My claim was denied years ago. Is it too late?
Possibly, though not always. Limitations periods vary by claim type, and certain facts affect when the clock started. A short review can tell you whether anything remains.
Your Policy Was a Promise. Hold It to That.
You paid premiums for years on the understanding that the company would be there when something went wrong. A denial letter does not change what you bought.
Templeton Law Firm has represented West Texas policyholders since 1998 from its office at 905 S. Abe Street in San Angelo. Call 325-482-9120 or schedule a consultation about your denied claim to have the denial reviewed against your policy.
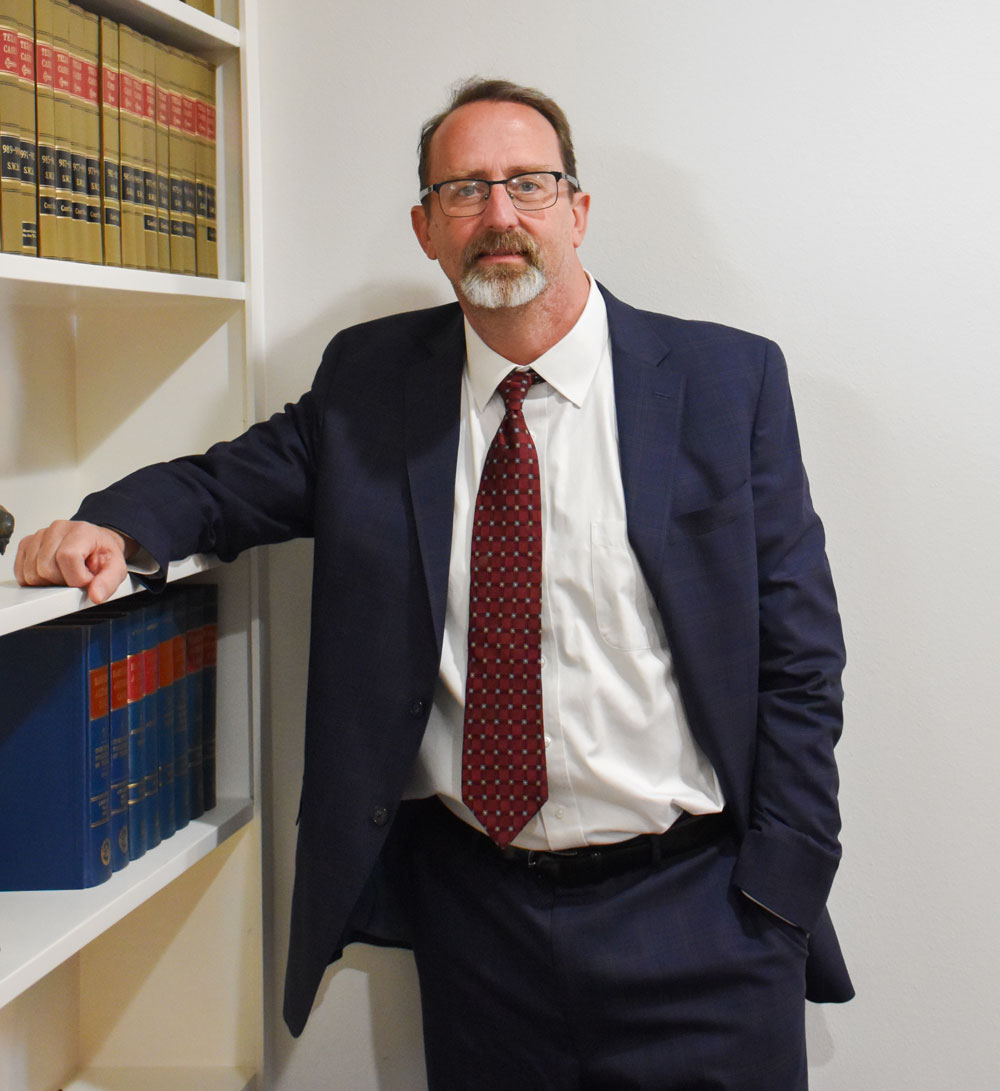
Scott Templeton
Attorney
We represent clients in west and central Texas in personal injury claims, business disputes, life insurance and property insurance claims, and employment claims. We are a litigation firm with 100% of cases oriented toward litigation and dispute resolution in favor of our clients. Our aim is to achieve outstanding results for our clients and serve the individuals and businesses in our community. For Spanish speaking clients, the Attorney and staff at Templeton Law Firm are bilingual.
Author's Bio